
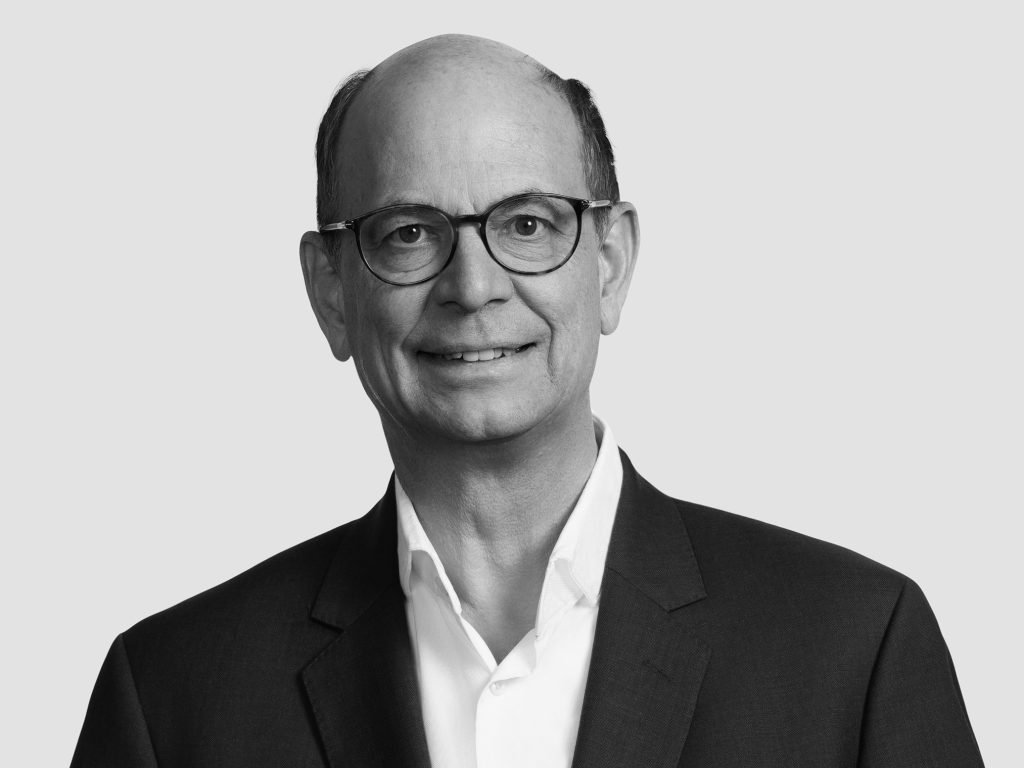
What keeps a renowned M&A lawyer energised after thirty years in the game? For Dirk Meeus, global co-head of M&A at A&O Shearman, it's never been about the paperwork. It's the complexity, the emotions and the sheer number of moving parts that make every deal irresistible – and his ability to hold onto the client's North Star amid all of it has made him one of Belgium's most respected dealmakers.
Dirk Meeus has spent more than three decades at the heart of Belgian and cross-border M&A, and today serves as global co-head of M&A at A&O Shearman. Across a wide-ranging conversation, three threads kept surfacing: his fascination with the human emotions that drive – and derail – transactions; his appetite for high-stakes, genuinely complex situations; and his conviction that the best dealmakers never lose sight of the client's true objective, however deep the legal detail or however sophisticated the technology in the room. What follows is a portrait of a lawyer who has built a career on keeping his eyes on the horizon while everyone else is staring at the map.
High stakes and human puzzles
Dirk didn't grow up around lawyers. "I don’t come from a family with a legal background, so all of this was fairly abstract to me", he says of his early career choice.
What drew him in, he explains, was the international dimension and the sheer intensity of the work:
"Deals are high-stakes situations. You get to solve complex problems, and that gives me a great deal of energy. When others say, 'That's the most difficult part, that can't be done' – we have the privilege of finding a way through, moving from one complicated situation to the next. Every situation is different, with different people, dynamics and challenges. That's what keeps me energised."
Ask him what actually makes a deal complex, and the answer isn't cross-border structuring or deal size – it's people. "What I've noticed is that it always comes down to human interaction. There's a technical layer to this job, of course – if that's all I cared about, I would have become a tax lawyer. But it's fundamentally a human situation: different shareholder groups, different interests, and different perspectives around the table. That's what I find fascinating, alongside the technical skills and legal knowledge."
That tension, he argues, is what separates good lawyers from great ones. "A good M&A lawyer has to be technically excellent: you need to know the law and work through every detail with precision. But you also have to be creative, able to think outside the box, and understand the wider commercial context as part of the bigger picture. Plenty of lawyers are very strong technically and very good with detail, and others are highly creative but miss the finer points. You need both."
Add to that the sheer range of disciplines that converge in a single transaction – tax, employment law, environmental law, antitrust – "and the more facets a deal has, the more complicated it becomes. Which also makes it more enjoyable."
From Bruges to Michigan to Manhattan
Dirk traces much of his instinct for the human side of dealmaking back to formal negotiation training in the United States, an experience he still describes vividly. "I've taken several negotiation courses over the years, focusing on how to approach different situations and dynamics. At the time, the American approach was quite new to me. Practice negotiations were filmed, cameras everywhere, followed by detailed feedback on your communication style, body language, and overall approach. It was a very valuable exercise."
That American chapter included a year studying in Michigan – not the obvious path for a Belgian lawyer, he notes, but one shaped by an earlier, smaller leap: two years studying in the French-speaking part of Belgium, largely because that's where he met his wife. "It was my first experience studying in another language. It may have been a relatively small first step within Belgium, but it gave me a real appetite to go and explore different environments, cultures and ways of thinking." Michigan followed naturally from that same instinct.
Decades later, that Midwest connection resurfaced in one of his most recent cross-border mandates: advising Puratos, a Belgian company in the bakery sector, on its deal with Dawn Foods, headquartered in Ann Arbor, Michigan – with much of the negotiation actually taking place in Chicago. It's exactly the kind of transatlantic deal flow that, Dirk says, underscored the strategic rationale for the combination that created A&O Shearman (The merger between the British law firm Allen & Overy and the American Shearman & Sterling was completed on May 1, 2024, and together they have formed the combined firm A&O Shearman, ed.).
"I don't think we would have handled the Puratos transaction the same way if we hadn't merged. Three-quarters of the target's business was in the United States, primarily in the Midwest, so the transaction required a genuine US platform and expertise to run a deal of that size, covering production, employment law, environmental and antitrust issues, the full spectrum of M&A. Without the combination, we simply wouldn't have had the same credibility."
Read also: A&O Shearman Belgium named Law Firm of the Year at Chambers Europe Awards
As global co-head of M&A, Dirk now regularly travels to the US – usually pairing New York with one other US office, compressed into a single week to limit time away from Brussels – for both deals and internal firm matters.
Despite the increasingly international nature of his work, Dirk still sees relationships as an important foundation of a successful M&A practice. Having spent his entire career with the same firm, he has seen first-hand the value of stable teams of lawyers and long-term client relationships. "Working with clients with the same teams over many years, you get to know the business, but also the people behind it. You see companies evolve, you help them through different strategic moments, and in many cases you grow alongside them. That's where the real trust comes from."
When ego enters the room
For all the technical firepower a top M&A practice can bring to bear, Dirk is adamant that most deals don't fail – or nearly fail – over legal or financial technicalities. They fail over people. Asked how many mistakes still get made in these processes after thirty years, his answer is immediate: "It's rarely purely about the hard business objectives, or technical, legal or financial issues. Far more often, it comes down to emotions and egos. Different expectations, sensitivities and personalities coming together under considerable pressure."
He illustrates the point with a family-business mandate that stayed with him: a Belgian shareholding structure involving a Spanish family, where a fourth generation voted to sell against the wishes of the third. "It was a hundred-year-old family business, with members of the younger generation reaching a different conclusion from the generation before them about whether the business should be sold. That created enormous tension and that's what makes this work so absorbing. You have to read the situation and find where the real problem sits, right in the middle of it all. As they say in New York: you can't make this stuff up."
So what does an M&A lawyer actually do when emotions take over a negotiation? For Dirk, the answer is almost deceptively simple. "You take a break. A time-out is one of the most important tools in any negotiation. Sometimes you need to pause rather than push through and risk allowing tensions to escalate. You let the emotions settle."
It's a small piece of advice, but one that runs through everything else he says about managing complex, high-pressure deals: de-escalate first, negotiate second.
Losing the forest for the trees
If emotion is one recurring threat to a well-run deal, information overload is the other and Dirk sees it accelerating fast. Looking back at how the profession has changed since he started, technology tops the list. "When I began as a young lawyer, we didn't even have computers – the fax machine was just introduced. Since then, the pace of technological change has been extraordinary, culminating most recently in the rapid development of AI."
But more data and more sophisticated tools, he warns, create their own risk: losing sight of the client's actual objective amid an ever-expanding pile of reports and consultants.
"In a major transaction, you might have thirty, forty, fifty work streams running at once. The real skill is bringing them all together and distinguishing what matters from what does not, always in light of your client's objectives. That's the North Star – never losing sight of the forest for the trees. That's the value you bring."
He offers a recent, very concrete example of how AI-supported analysis still needs to be combined with experienced human judgment. On one deal, a seller-friendly draft contract was circulated internally for input – to HR, to the environmental team, to finance – with each department asked to flag concerns. "That team had just started using Copilot to support its review. Rather than receiving thoughtful input from the different business functions, we were suddenly presented with a hundred AI-generated suggestions each, most of which weren't workable. At a certain point you have to say: if we ask all of this, we might as well stop the deal right now. You have to pull it back to what actually matters. What’s the objective? Do we want to do this transaction? And consciously decide not to ask certain things."
That same tension – how to let young lawyers use AI without losing the fundamentals – is central to how Dirk thinks about mentoring the next generation. Coaching junior talent, he says without hesitation, is one of the things he enjoys most about the job. "Working with young people is a genuine privilege. Every year in Brussels we bring in ten or fifteen 24-year-olds, all with fresh perspectives and considerable ambition, and it's a really rewarding process. The AI environment obviously makes that more challenging in some ways. Young lawyers used to do a lot of basic, repetitive work, and that's how they learned the craft. A lot of that work can now go straight into an AI tool, so they need to be trained differently. The challenge is making sure they still learn the judgement, creativity and people skills that ultimately make a good M&A lawyer."
He's pragmatic about where the technology genuinely helps: "Nobody is upset about not spending the night reading a hundred contracts to check for a change-of-control provision. If AI can perform that task accurately and efficiently in a couple of hours, let's embrace it, and get some sleep. But judgement, negotiation skills and the ability to remain focused on the client’s North Star still have to be learned through experience, coaching and exposure."
Bold moves and the next chapter of M&A
Zooming out to the market as a whole, Dirk points to a clear shift in how boards approach acquisitions: fewer deals overall, but a growing willingness to commit serious capital when a target is genuinely strategic. "For a lot of corporates, small add-ons can be interesting – they help consolidate a market and so on. But increasingly, companies are grappling with much bigger strategic questions: should we be in the United States, should we be in China, what's the threat from a particular technology, how do we become energy-independent. And we're seeing more and more that this calls for a bold move."
Pressed on the chess-piece analogy – no more pawns, but a bishop being offered instead – he agrees, while noting that smaller moves haven't disappeared:
"Bold moves don't mean add-on acquisitions disappear. Closing a factory, shifting production to a more efficient site, letting people go; that kind of consolidation is still very much part of the picture. But we're seeing more of the bigger strategic moves too. And frankly, as M&A lawyers, we like that."
He also sees particular opportunity in the Belgian and Benelux small-and-mid-cap space, where succession planning is often stalling and scale is sometimes just short of what's needed to make a business sustainable on its own. That, he argues, is precisely where private equity has a role to play.
"There's still considerable potential in the Belgian small-cap and mid-cap segment, particularly where businesses face succession or scale-related challenges. Private equity can play an important role by providing capital, supporting consolidation and helping businesses become even more successful. Players like Waterland are a good example. Buy, build and sell: that's the name of the game."
Roughly half of his own practice, he notes, is now private equity-related, and he's quick to point out how differently a ‘North Star’ is defined in a PE context versus a corporate one: financing structures involve leverage rarely seen in corporate deals, management incentive plans look completely different from corporate shareholding, and targets tend to be assessed on a standalone basis rather than for synergies.
"The typical private equity discussion when looking at a new investment is: how do we sell this within five years, and who are the likely buyers? In an industrial, corporate context, the target usually needs to be fully integrated within five years. The North Star sits in a different place."
Antitrust clearance, he adds, also tends to be simpler in PE deals, since sponsors are less likely to already operate in the same sector – whereas corporate acquirers, buying something closer to their existing business, face more regulatory scrutiny and, increasingly, geopolitical risk. He recalls one deal where war broke out in Ukraine during the regulatory approval period, sending energy prices through the roof and hitting the target's results before the transaction even closed. It’s a reminder of how external shocks can reshape a transaction mid-stream.
Asked what advice he'd give to a young M&A lawyer just starting out, Dirk circles back to the same balance he described at the very start of the conversation: precision and curiosity, held together. "It's that combination of an eye for detail, accuracy, and creativity – and actively seeking that out. Be curious, but at the same time be very precise. Some young lawyers naturally gravitate towards one or the other; the real skill is holding both."
He points to his own path – a French-language stint in Belgium, a year in Michigan, admission to both the Brussels and New York Bars, a merger that reshaped his own firm – as proof that unplanned detours often pay off. "You never know how these things will evolve. When I took the New York Bar exam, I had no idea I would one day become a partner at a firm that would later merge with a leading US firm. Seek out different experiences, different cultures, different countries. Be open to opportunities that are not part of the standard path, experiment a little and always look for a way to contribute something of value."

